For business owners
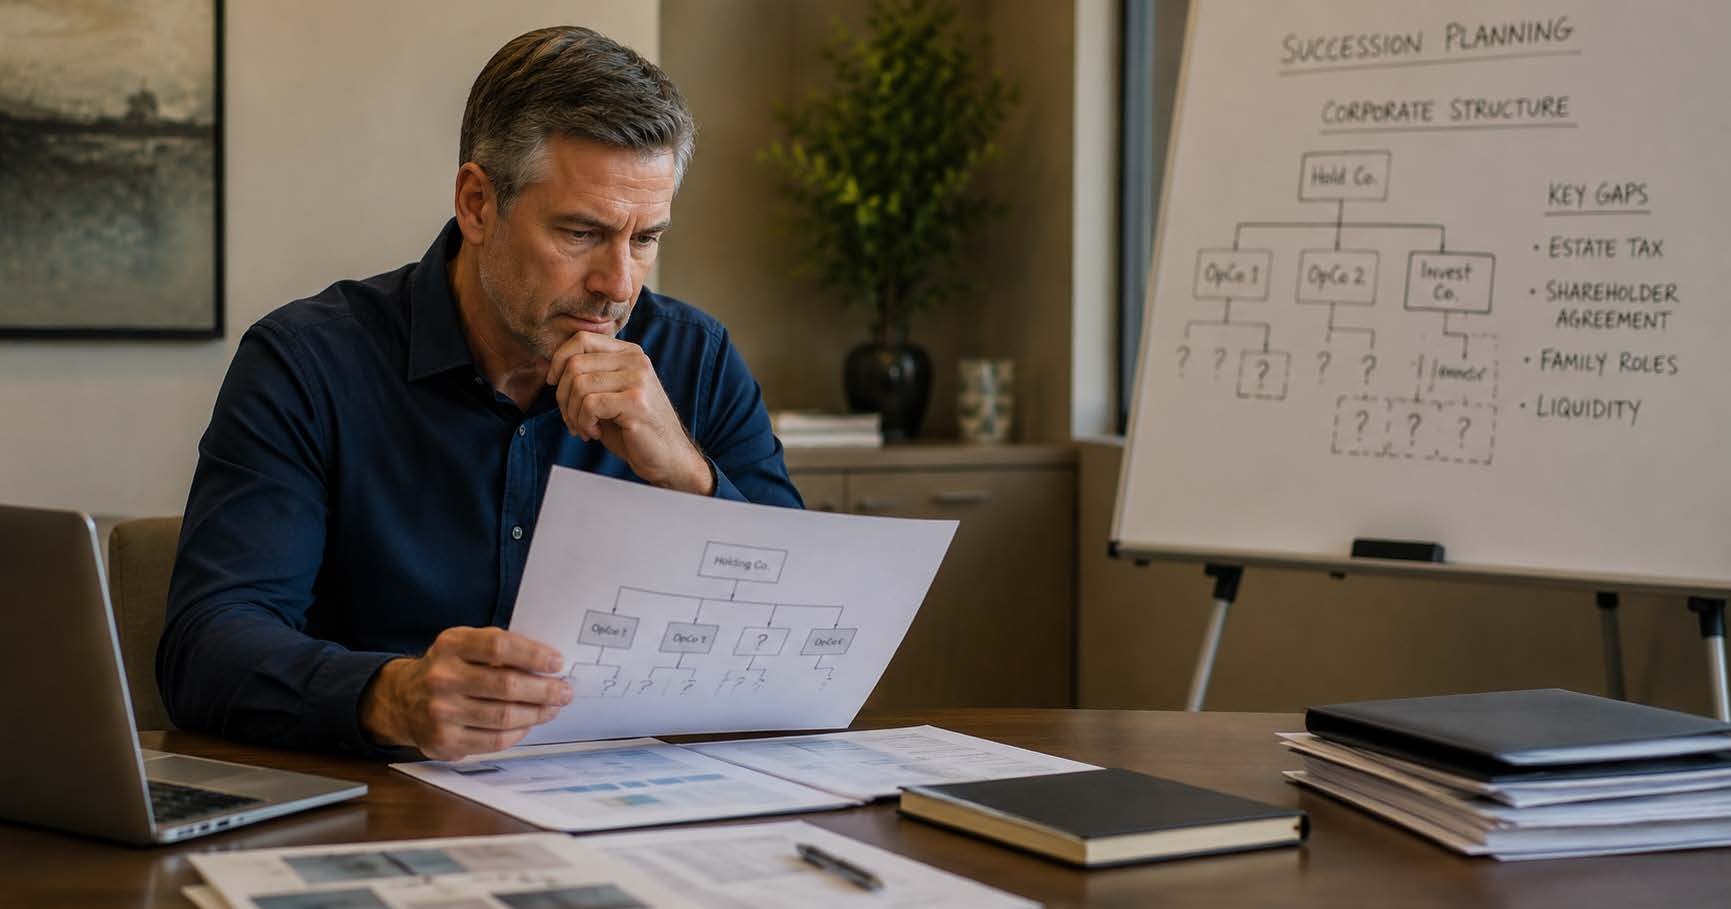
Most Ontario owners set up their corporate structure for operational reasons: tax efficiency while growing, creditor protection, income splitting. The estate and succession implications were rarely part of the original conversation.
As retained earnings accumulate and family circumstances change, a structure that worked during growth can quietly build an estate tax liability nobody has mapped. This review answers one question: does your structure support the transfer you intend?
An operating company (OpCo) runs your business. It signs the contracts, employs the staff, earns the revenue and carries the business risk. A holding company (HoldCo) runs nothing. It owns things: usually the shares of your OpCo, plus the surplus cash, investments, real estate or life insurance you move out of the business.
The reason to separate them is simple. Money sitting in your OpCo is exposed to everything that can go wrong in the business. Money moved up to a HoldCo is further from those risks and easier to plan with.
| OpCo (operating company) | HoldCo (holding company) | |
|---|---|---|
| What it does | Runs the business day to day | Owns shares, investments and insurance |
| Exposure to business risk | High: lawsuits, creditors, contracts | Lower: separate from day-to-day operations |
| Where surplus cash belongs | Only what the business needs to operate | Profits the business does not need, moved up |
| Role in your estate plan | Often the company passed to a successor or sold | Often where the estate freeze, corporate life insurance and capital dividend account are planned |
What a HoldCo does not do: it does not remove the tax at death. When you die, you are taxed as if you sold your shares, HoldCo shares included, at today’s value, unless they pass to your spouse. Your structure decides how large that bill is, who controls the companies afterward and whether there is cash to pay it. That is what this review maps.
Three questions to ask your accountant: Is surplus cash building up in your OpCo? Which company owns your corporate life insurance? When was your structure last reviewed against your estate plan?
The short answer
A HoldCo / OpCo Structure Review examines how your operating and holding companies, share classes, retained earnings and insurance are arranged, and whether that arrangement supports your estate and succession plan. You receive the specific gaps, what each one costs at death and the changes that would fix them, coordinated with your accountant and corporate lawyer.
The structure of your corporation determines four things at death: who controls the business, who benefits economically, when the tax is triggered and how large it is. Get it right and ownership transfers cleanly. Get it wrong and the default rules decide for you.
Operating company only. All value, retained earnings and assets sit in one company. Simple while growing, but at death everything triggers at once, with no separation and few options.
A holding company added. Surplus can move to the holding company, away from the operating company’s business risk, where it can hold investments and insurance positioned for estate and succession planning.
Insurance in the wrong entity. A policy owned personally or by the operating company when it belongs in the holding company can miss the capital dividend account, face creditor exposure and fail to fund succession as intended.
Share structure and control. Voting and non-voting shares, share classes and ownership percentages decide who controls what at death. If they have never been reviewed against your succession plan, the result may differ from what you intend.
01
A focused conversation about your corporate structure, assets, family situation and goals. No forms and no product discussion.
02
We review corporate documents, share structure, minute books where available, shareholder agreements and retained earnings, confirming the numbers with your accountant.
03
We identify the specific gaps, such as insurance in the wrong entity or surplus exposed in the operating company, and what each one costs at death.
04
We present the changes that would reduce your exposure and support a clean succession, with the tax effect of each.
05
Where restructuring is recommended, we work with your accountant and corporate lawyer so the structure, documents and insurance point the same way.
It separates your business into an operating company that runs the active business and a holding company that owns the operating company’s shares and holds surplus assets. It matters for asset protection, tax deferral, insurance ownership and estate freezes.
Retained earnings increase the value of your shares, which increases the capital gain at death. Taking them out of the corporation can also be taxed again as a dividend unless post-mortem planning is done.
In most cases, yes. A new holding company, an estate freeze or new share classes can change who controls what and how assets flow through your estate. Your structure and your will must be aligned.
Book a free 30-minute call. We will look at how your companies are set up and whether a full review makes sense. No obligation.
General educational information. Legal, tax and insurance decisions require advice appropriate to your circumstances.
Eagle Wealth Partners
Preserve Wealth. Protect Legacy.
Serving families and business owners across Ontario. Markham, in person and online.
Contact
Sami Majdalani is a licensed life and accident and sickness insurance agent in Ontario. Verify my licence on FSRA’s website. Insurance and segregated fund contracts are placed through HUB Financial, a managing general agency. Eagle Wealth Partners is paid by commission from the insurers whose products clients buy, and may also receive bonuses or other incentives from insurers. A full disclosure of the insurers we represent, how we are paid and any conflicts of interest is available on request.
Segregated fund contracts are individual variable insurance contracts issued by insurance companies. Any amount allocated to a segregated fund is invested at the risk of the contract holder and may increase or decrease in value.
Information on this site is general and is not legal, tax or insurance advice for your situation. Planning is implemented with your legal and tax professionals. © 2026 Eagle Wealth Partners Inc.